The Federal Government has said it will not release specific details of how funds obtained under its $5bn financing arrangement with First Abu Dhabi Bank will be spent.
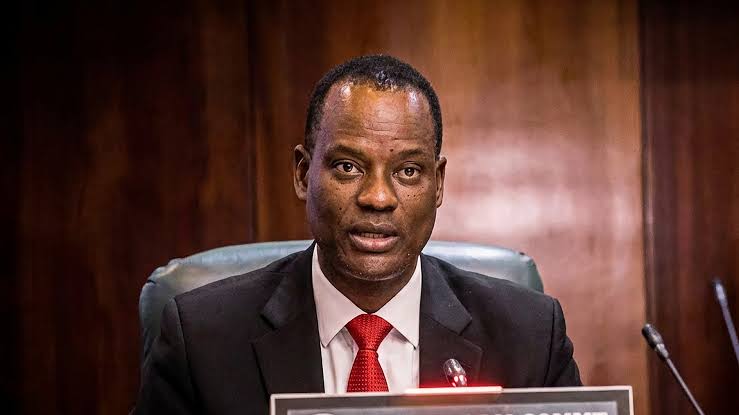
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, stated this on Wednesday during a media briefing in Abuja, while defending the transparency and legality of the facility.
The government recently accessed about $1.5bn from the $5bn facility, which was approved by the National Assembly in March 2026. The financing is expected to support the 2026 budget, infrastructure projects and the refinancing of existing debt.
Responding to questions on whether the government would disclose how the money would be spent, Oyedele said there was nothing unusual about the facility.
“We will not publish how we are spending it. We will publish how we spend government money. There’s nothing special about that loan,” he said.
The minister questioned why the Abu Dhabi facility was receiving particular scrutiny when other sources of government borrowing, including World Bank loans, Eurobonds and Sukuk, had not attracted similar demands.
He also dismissed concerns that the transaction was carried out without proper approval, noting that it had been considered by the Federal Executive Council and subsequently presented to the National Assembly.
“What else can be more public than what you gave to the National Assembly?” Oyedele asked.
According to the minister, the government is drawing the funds in phases rather than accessing the entire facility at once in order to avoid paying unnecessary costs on money that has not yet been deployed.
He explained that the arrangement also differs from Nigeria’s traditional fixed-rate borrowing because its interest rate is flexible.
“This First Abu Dhabi Bank transaction is flexible rates. It means if rates go up, we pay more. If rates come down, we benefit more,” he said.
Oyedele said the government’s main objective was to use the facility to refinance more expensive debt and reduce its overall borrowing costs.
“So the objective is to use it to refinance expensive debt so you can save money,” he said.
The $5bn arrangement requires Nigeria to pledge securities worth about 133 per cent of the amount drawn as collateral.
The International Monetary Fund and Fitch Ratings have previously expressed concerns about the structure, particularly its transparency and potential implications for Nigeria’s sovereign debt.
The IMF has warned that derivative-based financing arrangements such as total return swaps can make financial obligations more difficult to track and value, while Fitch has raised concerns that the facility could increase debt risks and reduce transparency in public debt reporting.
Oyedele, however, said the government would provide further information on the transaction.
He disclosed that the Ministry of Finance and the Debt Management Office would publish frequently asked questions on their websites in the coming days to address concerns surrounding the facility.
“In the next few days, you will see on the website of both the Ministry of Finance and DMO the frequently asked questions about this particular debt or bond, just so everybody can please themselves,” he said.
The minister maintained that the facility had received disproportionate attention despite being subjected to the required approval processes.
“There’s nothing special about the loan,” Oyedele said.